We’re fond of saying “the stock market isn’t the economy”
around here, but artificial intelligence pretty much is the economy right now, and anyone with a retirement account is likely exposed to that boom’s effects on the stock market.
What are we to make, then, of Nvidia? It’s the leading AI chipmaker, and often acts as the industry’s central bank, but CEO Jensen Huang was forced to resign this week
over personal conduct and national security concerns. Meanwhile, the world’s richest man was just warning about a shakeout of other AI companies that don’t often make headlines — we’ll start with one that’s beating the odds today.
Read on to get caught up on Nvidia, read a bunch of interesting stories about retirement open enrollment. We’ll end with one of my favorite songs of the week in a minute. Have a great weekend! — Tony Wagner, newsletter editor | |
|
|
|
|
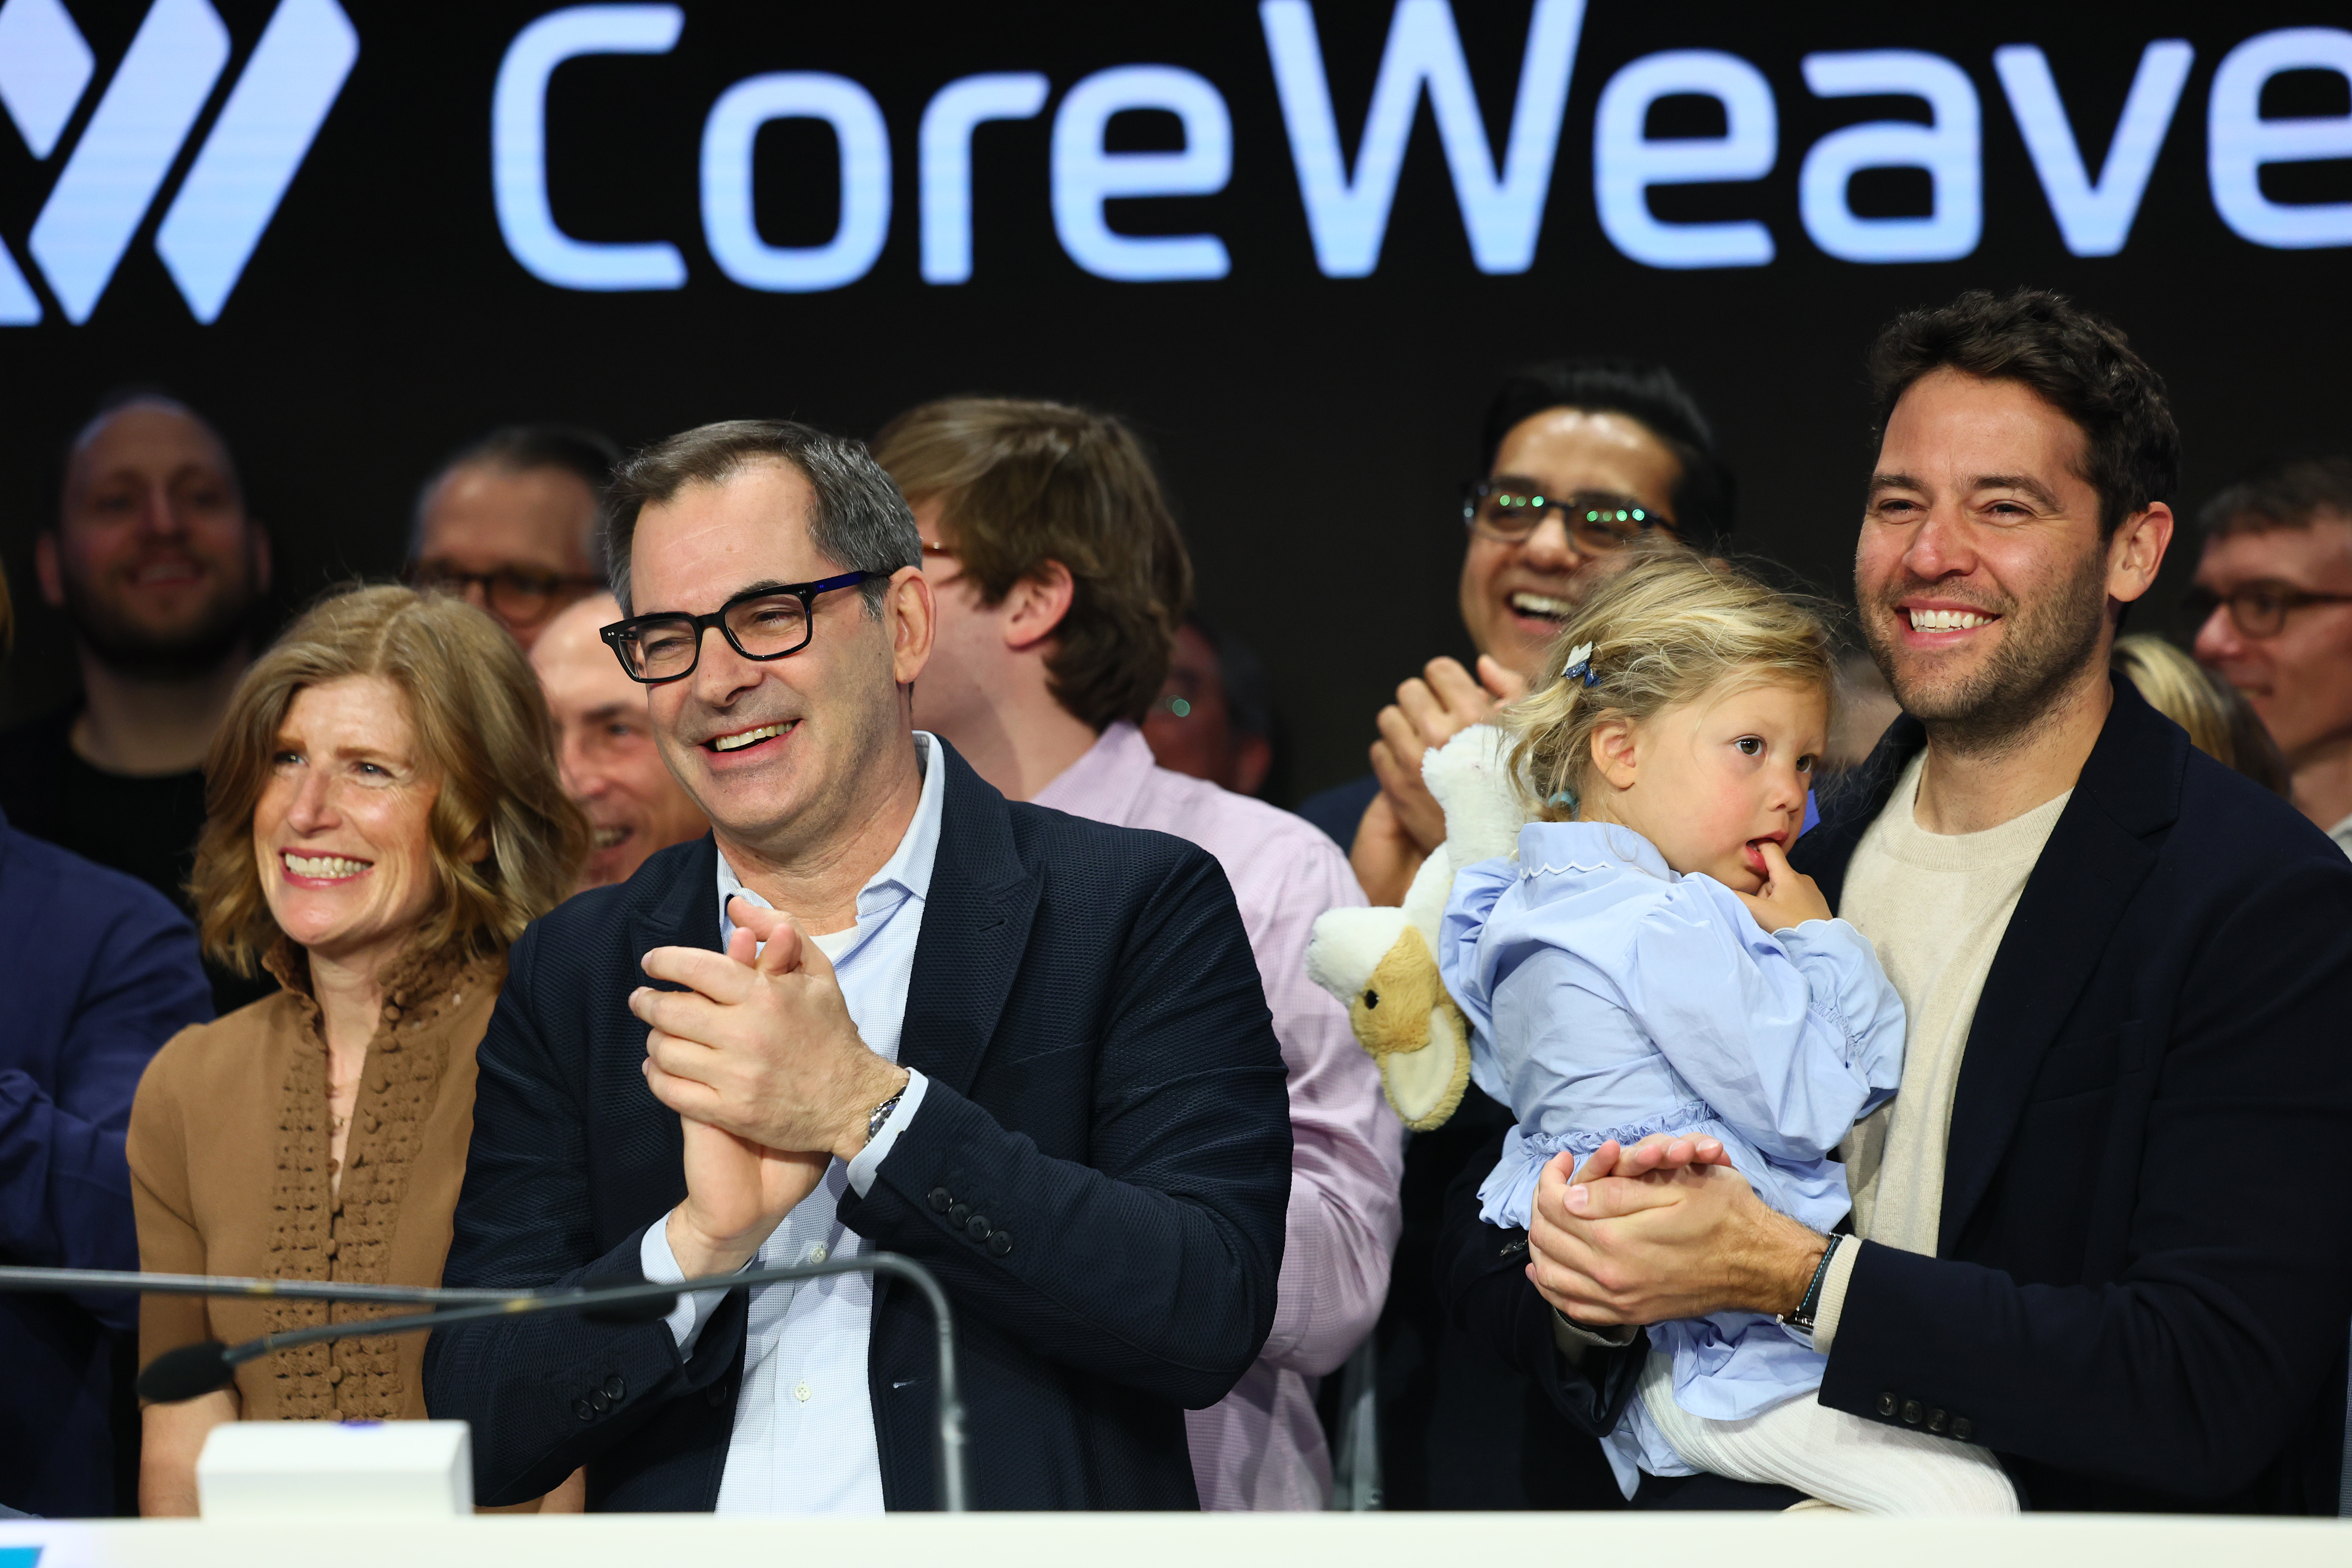 |
CEO Mike Intrator, second from left, rang the opening bell when CoreWeave went public last year. (Michael M. Santiago/Getty Images) |
What is CoreWeave and why is the stock market rising and falling on its earnings? |
The “neocloud” company is seen as a bellwether for the entire AI industry; it’s building a lot of data centers and taking on a lot of debt. Marketplace’s Sabri Ben-Achour explains. |
|
The stock market made up some ground after a brutal sell off when Coreweave dropped its earnings report.
Who? CoreWeave has been responsible for both widespread anxiety and reassurance among AI investors. Companies like Meta, OpenAI, or Microsoft all turn to a business like CoreWeave to build their data centers.
“CoreWeave is the architect for the AI era,” said Brent Thill, a managing director at Jefferies. “They’re the general contractor that puts together the data center, the power, the cooling the chips, the rack.”
Investors looked at CoreWeave as a bellwether for the country’s
entire AI buildout. A few months ago, they started to have qualms.
“There’s a lot of fear among investors that the AI trade is softening,” Thill said.
And the recent election spelled friction ahead for new data centers. | |
|
|
|
|
| The Nvidia affair Tales from retirement -
Doug Asbe and his wife retired early to avoid a Social Security cash crunch. Here’s how.
-
Your money | |
|
|
|
|
No clickbait, no AI summaries, no paywalls |
Just the best in business and economic news every single day. Your support makes it possible. | |
|
|
|
 |
(Aaron P. Bernstein/Getty Images) | “It feels immoral": Small businesses struggle with rising healthcare premiums |
Healthcare costs are rising faster than inflation. Some businesses told Samantha Fields it’s becoming increasingly untenable. |
This time of year is nerve-wracking for Cindy Wheeler.
As vice president and operations manager at Beacon’s Closet, which has four vintage and thrift stores in New York City, it’s her job to figure out health insurance for their nearly 50 full-time employees. It’s always a lot of work in the lead up to open enrollment. But this year has been something else.
When the business got its annual renewal letter from Anthem Blue Cross and Blue Shield this fall, Wheeler was stunned to see the premium increase: 59.5%.
“It seemed like a joke,” she said. “I was like, ‘Am I reading this right?’”
She was.
“I sent the letter to all my partners, and I have to say, the immediate reaction was incredible anger,” Wheeler said.
It’s also just way out of step with the annual increases Beacon’s Closet has seen in the past, and with how much employer premiums are projected to rise nationally. In 2026, the average healthcare premium employers pay rose 5%, according to a recent analysis from the health policy nonprofit KFF. Beacon’s Closet’s premium increased 8.3%.
“Which seemed awful,” Wheeler said. “But it was the best we could do.”
For 2027, early estimates project employer premiums are likely to rise roughly another 8-9%; more than double the
rate of inflation
, but nowhere near the nearly 60% increase that Anthem initially offered Beacon’s Closet.
“All the four stores combined, we pay about $600,000 a year for health insurance,” Wheeler said. “With that increase, it was going to be more than $1 million a year. And that is not sustainable. Like we cannot do that. We would go out of business.” | |
|
|
|
|
| Here are the Marketplace stories readers clicked on the most in our Daily Wrap newsletter this week. Sign up to get the latest news and numbers in your inbox every weekday evening.
| |
|
|
|
|
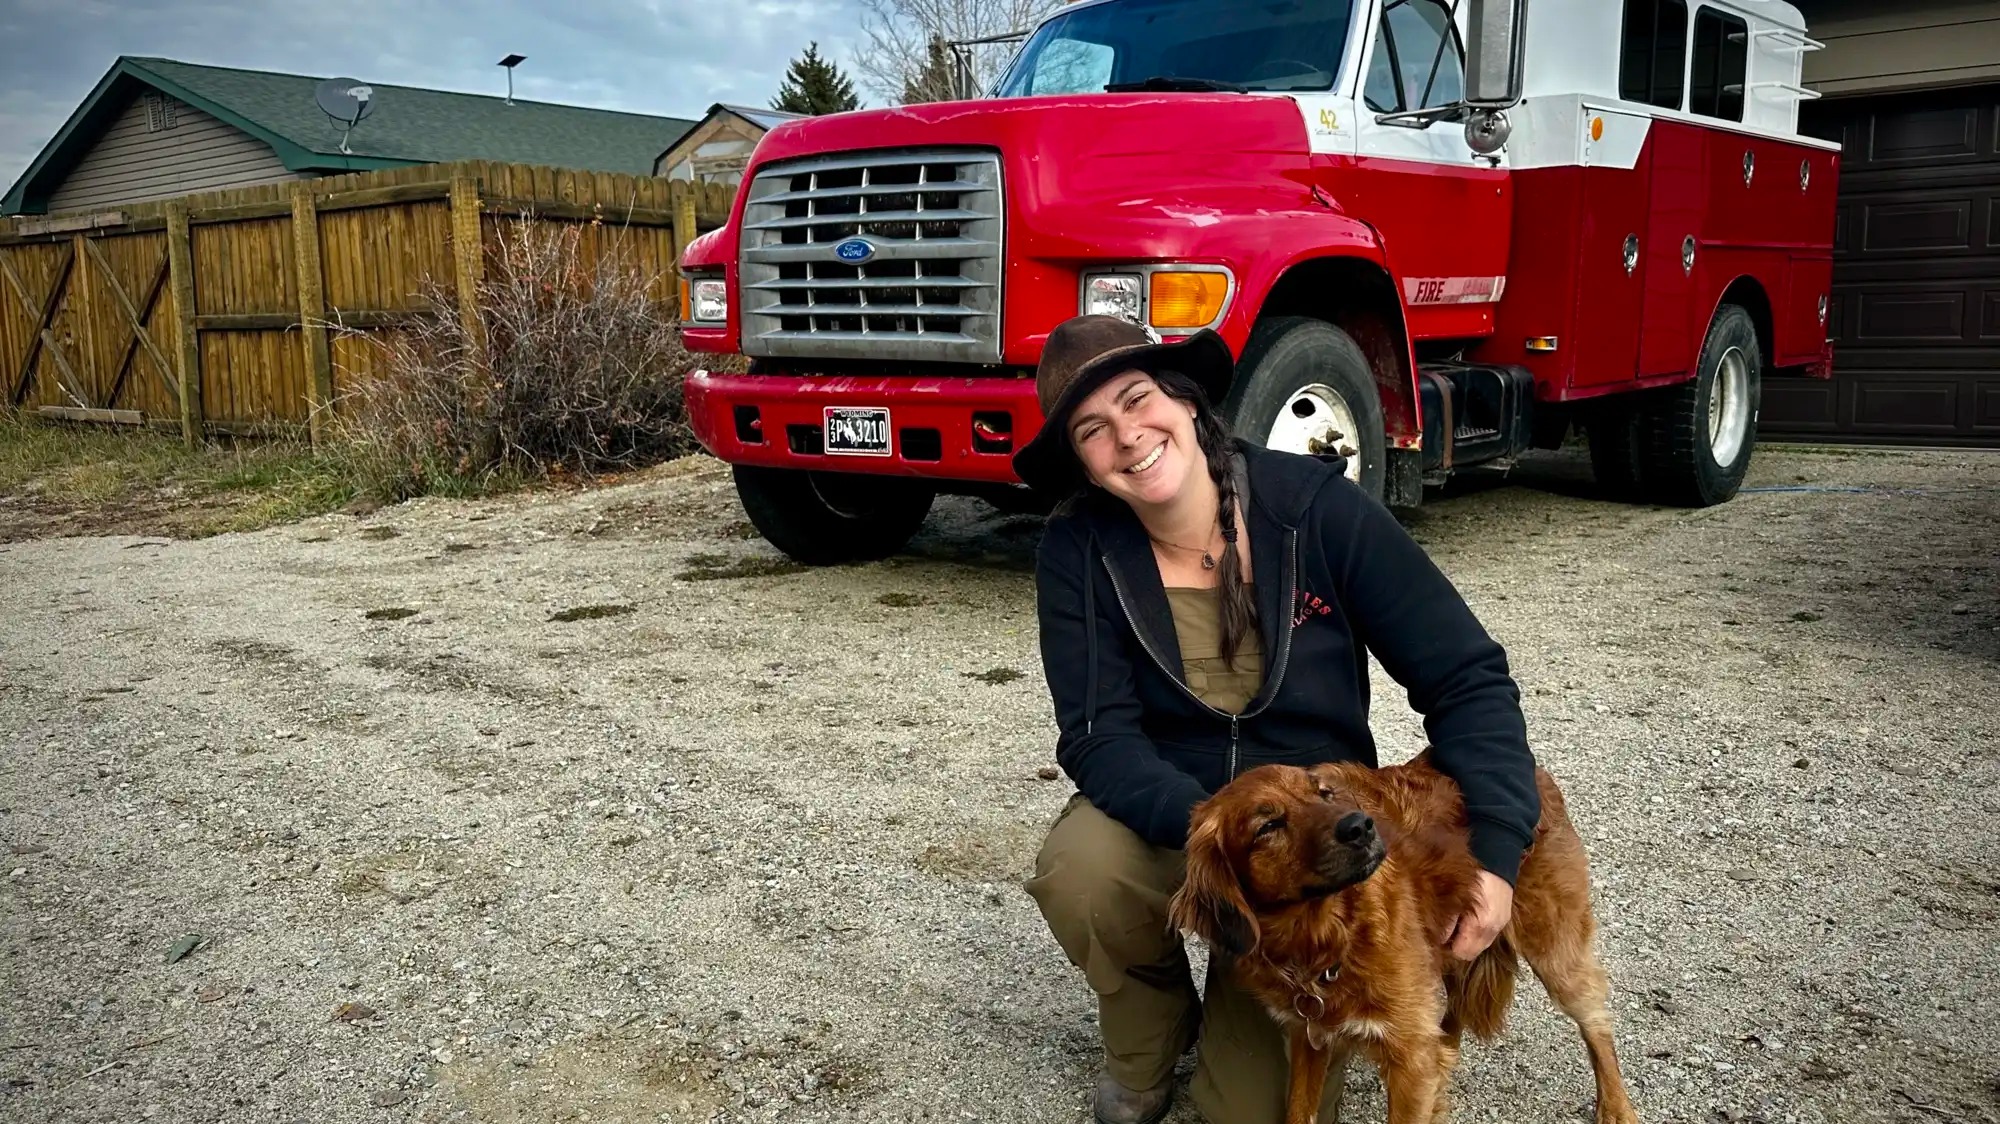 |
Rachel Daniels with her dog Nutmeg. (Caitlin Tan/Marketplace) | A growing Wyoming town faces a housing development crossroads |
A wave of new residents have come to Pinedale, Wyoming, since the pandemic. Local workers told Caitlin Tan it’s hard to afford housing in the mountain town, but development is tricky. |
|
A few blocks off main street in Pinedale, Wyoming, is a ranch-style three bedroom home. Rachel Daniels just moved in.
“So, a cute little sitting room, little gas fireplace,” she said as she walked through the house.
Daniels is house sitting for a woman who owns multiple homes in the area.
“This is all hers except for that bookcase — my bookcase,” Daniels said. “I brought four pieces of furniture.”
Her rent: pay the utilities and shovel the snow.
The house is for sale, just shy of half a million dollars. Daniels cannot afford to buy it, but house sitting is a way for her to stay in Pinedale, where she can keep hiking in the mountains and swimming in glacial lakes.
Pinedale has long been a ranching and oil and gas town. It has a couple thousand residents, but still no stoplight, Walmart, or fast food chains. It is one of the fastest-growing areas in the state.
The pandemic brought in a lot of people from out of state. Plus, 75 miles up the road is Jackson, Wyoming, where the average house is
around $7 million
. As a local saying tells it: Jackson’s billionaires are pushing the millionaires to Pinedale.
Home costs in Pinedale have increased by about $200,000 in recent years. As more people move in, it becomes trickier to figure out how to control development and build more housing that local workers can afford. | |
|
|
|
|
 |
Click to listen on your podcast app! (Ariel Aberg-Riger) | Final note |
Where there’s a crisis, there’s profit potential |
And the climate crisis is no different.
This season, Marketplace’s podcast “How We Survive” is exploring the disaster economy. From prediction markets where investors can bet on the weather or hedge against climate risk, to insurance companies and cleanup companies raking in dough, we’re finding out who benefits from extreme weather, and what it means for the rest of us. New episodes start next week. | |
|
|
|
|
|
| |
SONG OF THE WEEK | “Trillions” by DIIV |
|
| |
|
|
|
|
|
 |
(Fantasy) | |
DIIV rose to prominence during that era, and their new album is full of ironic jabs at the capitalistic system they’re trying to get by in, too. “We want to be able to make a living from our work. For us, “trillions” is just a living wage,” frontman Zachary Cole Smith told Billboard. “That’s our trillions, and we want that.” | |
|
|
|
|
| Take the Marketplace news quiz! |
| Listen to “Marketplace,” test your knowledge, brag to your friends. | |
|
|
|
Thanks for reading! If you enjoyed this newsletter, forward it to a friend. If this newsletter was forwarded to you,
subscribe to Marketplace newsletters here.
Got feedback for us? Just reply to this email. We can't get back to everyone, but we read it all. | | |
| |
|
|
|